

The Story Is Changing
TeraWulf is shifting from Bitcoin mining to AI, HPC and data-centre infrastructure. In Q2 2026, revenue reached $44.8 million, with 71% coming from HPC leases, versus almost none a year earlier.
The model is changing from mining Bitcoin with cheap power to securing power, building data centres, signing long-term AI/HPC leases and generating recurring revenue.
So, the key question is whether TeraWulf can turn this expansion into sustainable earnings and cash flow.
Power Is Becoming the Real Asset
TeraWulf’s emerging advantage is access to power, a critical resource for AI infrastructure. Lake Mariner already has 102 MW operational, with another 336 MW under construction.
The bigger opportunity is the 401 MW, 20-year Anthropic lease in Kentucky, worth about $19 billion over its term, with initial capacity expected in H2 2027.
TeraWulf has also secured up to 1 GW of utility capacity at its Muskie campus.
Overall, the company has indicated about 2,921 MW of potential IT capacity, including 839 MW contracted.
The strategy is becoming clear: secure power, build infrastructure and lock in long-term AI customers—potentially taking TeraWulf well beyond Bitcoin mining.
The Financial Picture Still Tells a Different Story
TeraWulf’s AI opportunity is large, but its financials remain weak.
FY2025 revenue was $168.5 million, with a $661.4 million net loss, $123.2 million operating cash outflow and $1.06 billion in capital investment.
H1 2026 revenue reached $78.8 million, including $53 million from HPC leases, but EBITDA and operating cash flow remained negative. In short, TeraWulf is spending heavily today to build a potentially much larger AI infrastructure business tomorrow.
Liquidity Helps—but Leverage and Dilution Matter
TeraWulf has substantial liquidity, but also significant financial obligations. As of June 30, 2026, it had $2.62 billion in cash and $3.03 billion including restricted cash, against about $3.02 billion of long-term debt and significant convertible notes.
The business is therefore highly capital intensive. Dilution is another concern: shares outstanding rose from about 420 million to 499 million between December 2025 and June 2026.
For investors, the key question is not simply how many megawatts or contracts TeraWulf adds, but how much sustainable cash flow and value those assets ultimately generate per share.
The Anthropic Contract Changes the Visibility
The 401 MW Anthropic agreement is a major step in TeraWulf’s transformation, providing far greater revenue visibility than its traditional Bitcoin-mining model.
But the contract is only the beginning.
Its value depends on TeraWulf’s ability to build the infrastructure, deliver the contracted capacity and manage the required financing.
The same applies to Lake Mariner and Muskie. Going forward, the market is likely to focus less on new announcements and more on converting contracted MW into operating assets, recurring revenue and cash flow.
The Biggest Risk Is Execution
TeraWulf must deliver its large projects on time and at viable costs, with Lake Mariner construction.
Large HPC contracts improve visibility but also increase customer concentration. At the same time, any slowdown in AI spending, higher financing costs or weaker data-centre economics could pressure valuations.
The Next Phase: Watch Conversion, Not Headlines
The next phase of TeraWulf’s story should be judged by execution rather than announcements.
Key markers are the commissioning of Lake Mariner’s CB-4 and CB-5, continued growth in HPC lease revenue, progress on the Anthropic project and development of Muskie’s initial 500 MW phase.
Equally important will be the company’s ability to fund expansion without excessive dilution and, ultimately, move toward positive EBITDA and sustainable operating cash flow.
The Technical Picture: An Important Zone
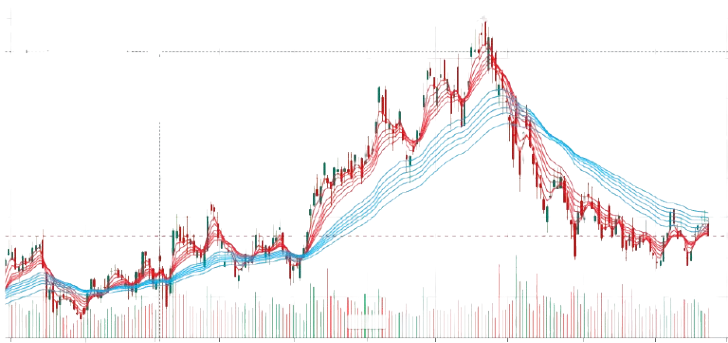
The stock remains in a volatile recovery phase.
With RSI around the mid-50s, the stock is neither oversold nor overbought, leaving the next directional move dependent largely on how it responds to the present levels.
Price Scenarios
These levels are scenarios, not predictions.
Over 2–6 months, a sustained move above $18.00–18.50 could shift focus toward $20–21, followed by $23–25.
Longer term, successful execution at Lake Mariner, Justified and subsequent campuses could open broader technical zones around $28–30 and potentially $35–40.
These are conditional technical and valuation scenarios—not fair-value estimates. Reaching the higher zones would require stronger earnings, cash-flow visibility and investor confidence.
The Investment Thesis Has Changed
TeraWulf’s thesis is shifting from Bitcoin mining and cheap power to AI/HPC infrastructure, long-term leases, recurring revenue and capital expansion.
The bigger opportunity is whether TeraWulf can secure power, attract long-term AI/HPC customers, finance new capacity and recycle capital for further growth.
Success could create a scalable infrastructure platform with recurring revenue, but debt, high capital needs, dilution, execution risks and AI-market uncertainty remain significant.
TeraWulf is therefore still a high-beta infrastructure growth story, not a mature data-centre business.
What Matters from Here
TeraWulf remains between key support and resistance levels, with the chart still in a recovery phase. The bigger trigger, however, is whether its contracted capacity converts into recurring revenue, positive EBITDA and sustainable cash flow.
TeraWulf is no longer primarily a Bitcoin story; it is increasingly a bet on whether its power advantage can support a durable AI-infrastructure business, while execution and financing risks remain significant.
Disclaimer:
This report is for research and educational purposes only and is not investment advice or a buy/sell recommendation. Technical levels are scenarios, not predictions. Financial information is based primarily on company filings and disclosures, while technical observations use market data through September 23, 2026.
TeraWulf is highly volatile and capital-intensive, with significant execution, financing, dilution, interest-rate, customer-concentration and AI-market risks. Readers should verify the latest company disclosures and market data before making investment decisions.
The writer holds no shares or securities of TeraWulf Inc and has no financial interest in the company.